Answer
What is a chargeback?
Quick answer
A chargeback is a card payment reversed by the cardholder's bank after the customer disputes it. The money is pulled back from the business, usually with a dispute fee, and the business can accept the loss or respond with evidence. The issuing bank decides who wins.
Updated October 2026. Evergreen page — refreshed in place as facts change.
- Filing window
- 120 days
- Most Visa and Mastercard reasons
- Your response time
- 1–3 weeks
- Typical provider deadline per dispute
- Dispute fee
- $15–$20
- Stripe, Braintree, Shopify, PayPal; Oct 2026
- Ratio to aim for
- Well under 1%
- Of transactions; networks set thresholds
- Who decides
- The issuer
- Not you, and not your provider
- Fraud evidence rule
- CE 3.0
- Visa's Compelling Evidence, since 2023
- 3D Secure
- Liability shift
- Fraud disputes usually move to the issuer
- Auto-refund limit
- $1–$10,000
- Pre-dispute alerts, set by you at Anytime Capital
A chargeback is the card system's consumer-protection backstop, and for a business it is one of the most expensive ways to lose a sale: the money goes back, the goods usually do not, and a fee comes on top. This guide follows a dispute from the customer's call to the bank's decision, explains the reasons and the stages, and covers what prevents chargebacks and what wins them.
Payment methods on this page

How does a chargeback work, step by step?
A chargeback starts with the customer, not the business. Instead of asking you for a refund, the customer asks their card issuer to reverse the payment, and the issuer sends the dispute through the card network to your provider.
Customers can generally dispute for up to 120 days from the transaction or the expected delivery date for most reasons under Visa and Mastercard rules, so a dispute can arrive months after the sale.
From the moment you are notified, the amount is usually already out of your balance. You then accept the chargeback, or submit evidence before your provider's deadline, often one to three weeks, and the issuer reviews it and decides. Either side can sometimes escalate to pre-arbitration and then arbitration, where the card network itself rules.
The chargeback lifecycle
- 1
Customer disputes
They ask their card issuer to reverse the payment instead of asking you.
120-day window - 2
Issuer files
The chargeback goes through the card network with a reason code.
Reason code - 3
You're debited
Your provider tells you and takes the amount, usually plus a fee.
On notice - 4
You respond
Accept it, or send evidence before your provider's deadline.
Often 1–3 weeks - 5
Issuer decides
It weighs the evidence; some cases go on to arbitration.
Weeks
Alert, inquiry, chargeback, arbitration: what are the stages called?
Disputes come with their own vocabulary, and the name on the notice tells you how much is at stake and what to do next. Not every dispute passes through every stage: many end at the first chargeback, and a dispute you refund at the alert stage never becomes a chargeback at all.
| Stage | What it means | What you do |
|---|---|---|
| Pre-dispute alert | The issuer or network warns that a customer has started a dispute | Refund now to stop the chargeback, with no dispute fee |
| Retrieval request (inquiry) | The issuer asks for the transaction record before deciding | Send the receipt and order details quickly |
| Chargeback | The issuer reverses the payment with a reason code | Accept it, or prepare evidence |
| Representment | Your evidence, sent back to the issuer through your provider | One page that answers the reason code |
| Pre-arbitration | The issuer rejects your evidence and the dispute continues | Decide whether a second round is worth it |
| Arbitration | The card network rules on the case | Weigh the network's fees against the amount at stake |
Why do customers file chargebacks?
Card networks use dozens of reason codes, but nearly every dispute falls into one of a few plain-words categories. Knowing which one you are facing tells you what evidence will answer it.
Not every dispute is fraud. A large share comes from customers who do not recognise the name on their statement, forgot a subscription renewed, or never got a reply from support. Those are the disputes a business can most easily prevent.
| Reason | What the bank is claiming | Evidence that answers it |
|---|---|---|
| Fraud | The cardholder did not make or authorise the payment | 3D Secure result, matching address and device data, past undisputed orders |
| Not received | The goods or service never arrived | Tracking showing delivery, proof of service, access logs |
| Not as described | What arrived was different or defective | The listing, photos, terms, and messages with the customer |
| Duplicate or incorrect | Charged twice, or charged the wrong amount | Records showing two separate orders, or the correct amount |
| Cancelled subscription | A recurring charge continued after cancelling | Accepted terms, renewal reminders, no cancellation on record |
| Credit not processed | A promised refund never arrived | The refund record, or the policy showing none was due |
What is friendly fraud?
Friendly fraud, also called first-party misuse, is a chargeback filed as fraud on a purchase the cardholder actually made or allowed: a family member used the card, the customer forgot the purchase, or regretted it and found the bank easier than the returns page. To the issuer it looks the same as a stolen card, so the burden falls on the business to show otherwise.
It is also the dispute type where records matter most. A receipt the customer was emailed, a delivery confirmation to their own address, a login to the account that placed the order, or earlier undisputed orders from the same card and device all point to a real customer. Visa's Compelling Evidence rules, covered below, were written for exactly this case.
- Signs of friendly fraud: a fraud claim from a returning customer, delivery to the cardholder's own address, or use of what was bought after delivery
- Signs of real fraud: a new customer, mismatched billing and shipping details, rushed shipping on resellable goods, or several cards tried in a row
What does a chargeback cost a business?
A lost chargeback costs the sale, whatever you shipped, and a dispute fee that many providers charge whether you win or lose. Time spent answering it and the processing fee on the original sale come on top.
Disputes also count against you. Card networks run monitoring programs for businesses whose dispute ratio climbs, and most businesses aim to stay well under 1% of transactions; the networks set and change their own thresholds.
Put together on one order, the arithmetic is stark. Lose an $80 dispute at a provider charging Stripe's published $15 dispute fee and 2.9% + 30¢ processing, and the business is out $80 of revenue, $15 in fees and the $2.62 processing fee on the original sale, which most providers keep: $97.62 before counting the goods themselves (October 2026 rates).
Visa folded its separate fraud and dispute monitoring programs into one, the Visa Acquirer Monitoring Program (VAMP), in 2025. It counts fraud reports and disputes together against a business's card-not-present sales, and its merchant thresholds tightened in April 2026. Mastercard runs its own excessive-chargeback program. A business that crosses a threshold faces fines passed on by its acquirer and, in the worst case, the closure of its merchant account.
| Provider | Dispute fee |
|---|---|
| Stripe | $15 per dispute, plus a counter fee to contest one (refunded if you win) |
| PayPal | $20 per chargeback |
| Braintree | $15 per chargeback |
| Shopify Payments | $15 per chargeback (US) |
| Square | No dispute fee today; the processing fee is lost if you lose |
How do you prevent chargebacks?
Most preventable disputes come from confusion rather than fraud, so prevention starts with making the payment easy to recognise and the business easy to reach. Fraud tools handle the rest.
Pre-dispute alerts are the most underused tool. Card networks offer services that warn the business when a customer has started a dispute, which gives you a window to refund before it becomes a chargeback, with no fee and no mark on your ratio.
- Use a statement descriptor customers will recognise, ideally with your business name and a phone number or website
- Answer support messages quickly and refund clear problems before the customer goes to their bank
- Send renewal reminders for subscriptions and make cancelling easy
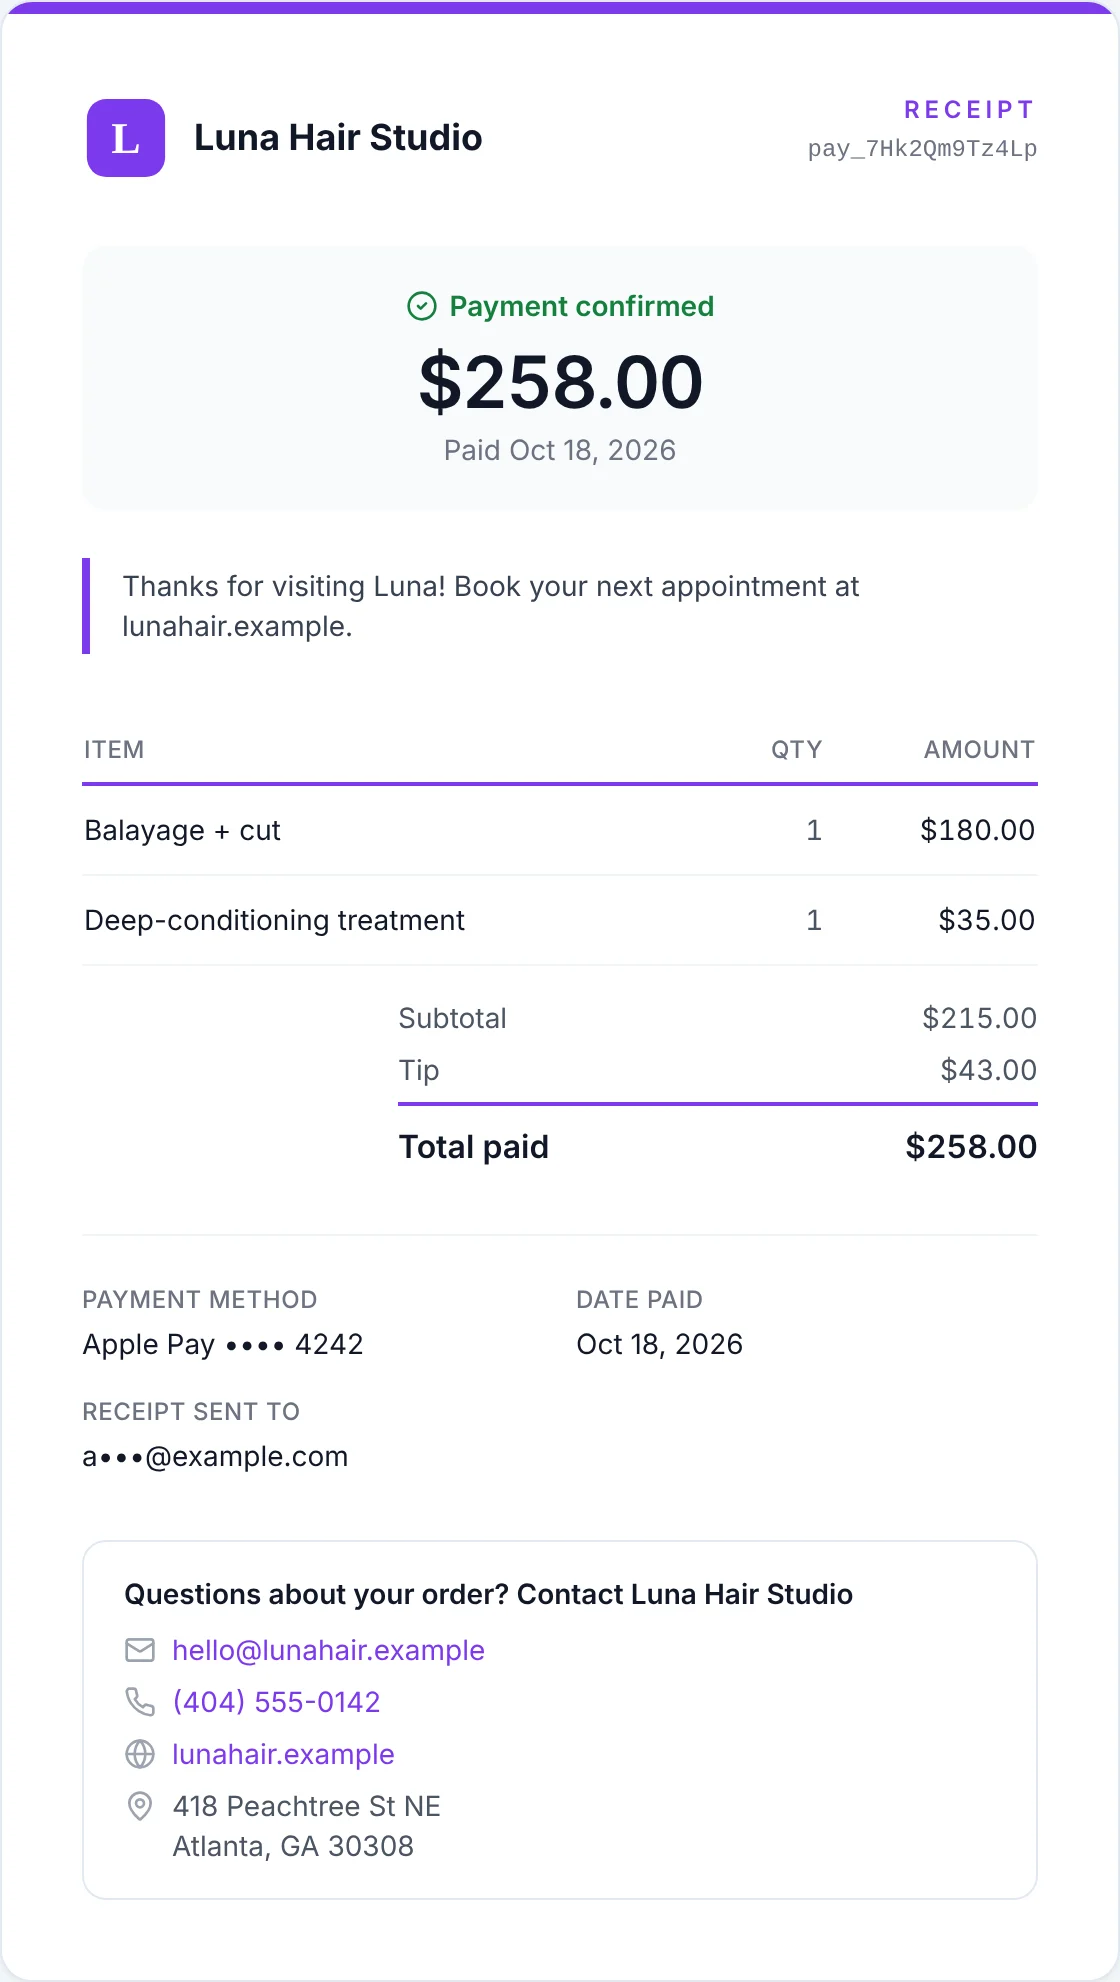
- Keep tracking numbers, delivery confirmation and signed work orders
- Require 3D Secure above an amount, which usually moves liability for fraud disputes to the issuer
- Screen payments before they are charged and block the riskiest ones
How do you win a chargeback?
Respond before the deadline, answer the specific reason code, and keep it short. Issuers review many disputes a day; a one-page response with the right three documents beats twenty pages of everything.
For fraud claims from returning customers, Visa's Compelling Evidence 3.0 rules, introduced in 2023, let a business answer with matching details, such as the device or IP address, from earlier undisputed purchases by the same customer.
Under those rules the earlier purchases generally need to be at least two undisputed payments on the same card from 120 to 365 days before the disputed one, sharing details such as the IP address, device, account login or delivery address. Your provider's dispute form usually asks for exactly these fields, so keeping order records with that data is what makes the rule usable.
- Match the evidence to the reason: delivery proof for 'not received', the listing for 'not as described'
- Include the receipt, the customer's details and any messages showing they used or acknowledged the purchase
- Show the terms or refund policy the customer accepted at checkout
- Accept the disputes you cannot win, and spend the time on the ones you can
Answering a dispute, in five moves
- 1
Read the reason
Find the reason code and your provider's deadline on the notice.
Day 1 - 2
Pick the evidence
The two or three documents that answer that reason, not everything.
Receipt, proof, terms - 3
Write one page
What was bought, when, by whom, and why the claim does not hold.
- 4
Submit early
Before your provider's deadline, which is shorter than the network's.
Days, not weeks - 5
Fix the cause
Log the reason, then change the descriptor, policy or process behind it.
Every dispute
How Anytime Capital Payments handles disputes
Dispute tools are included on every account. Every card payment gets a 0–100 risk score before it is charged, and you can decline payments scoring 90 or more, 75 or more (the default) or 60 or more, require 3D Secure above an amount you choose, block cards from selected countries and cap the amount of a single payment.
When a bank warns that a dispute is coming, payments at or under a limit you set, from $1 to $10,000, are refunded in full automatically before they become chargebacks. Real disputes sit on one page with the bank's reason explained in plain words, the evidence that wins that reason, and a response form that starts from what we already know about the order, with email alerts as the deadline approaches. Any dispute fee is shown in your dashboard.
Frequently Asked Questions
Is a chargeback the same as a refund?
No. A refund is something you choose to give; a chargeback is a reversal the customer's bank forces. A chargeback usually carries a dispute fee and counts toward your dispute ratio, which is why refunding a clear problem early is often cheaper than letting it become a chargeback.
How long does a customer have to file a chargeback?
For most reasons, Visa and Mastercard rules allow up to 120 days from the transaction or from the date the goods or service were due. Some cases, such as goods never delivered, can run longer, so keep records for several months after each sale.
Can a business dispute a chargeback?
Yes. Responding with evidence is called representment. You submit documents through your provider before its deadline, and the issuing bank decides. If it rules against you, some disputes can be escalated to pre-arbitration or arbitration, which carries its own fees.
Do you get the dispute fee back if you win?
It depends on the provider. Stripe refunds its counter fee when you win, per its published US pricing (October 2026); many providers keep the original dispute fee either way. Check your provider's terms.
What is a good chargeback ratio?
Most businesses aim to stay well under 1% of transactions, and lower is better. Card networks run monitoring programs with their own thresholds and fines, which they revise from time to time, so ask your provider which apply to you.
Can ACH payments be charged back?
Not in the card sense. ACH payments can be returned instead, for reasons such as insufficient funds or an unauthorised debit, under Nacha rules with their own time limits. Our ACH vs credit card guide compares the two risks.
Can a customer file a chargeback after getting a refund?
They can, and it usually happens when a refund is still on its way as the customer calls the bank. Answer the dispute with the refund record, which normally settles it in your favour, and tell customers when to expect a refund on their statement, typically five to ten business days, so they do not dispute in the meantime.
How long does a chargeback take to resolve?
Usually weeks to a few months. You typically have one to three weeks to respond, the issuer then reviews your evidence, and a dispute that goes on to pre-arbitration or arbitration adds further rounds. The disputed amount normally stays out of your balance until the issuer rules in your favour.
Keep reading
Important Disclosures
- Third-party fees and product details cited on this page are each company's published US pricing, or industry-typical ranges, as of the date shown and may have changed. Check current pricing with the provider before you decide.
- Information on this page is general and educational — it is not financial, legal, or tax advice.
- Anytime Capital is a fintech company, not a bank. Payment processing, banking and payout services are provided by Anytime Capital's licensed partners. Rates shown are for US card payments; international cards, currency conversion and disputes may carry additional fees shown in your dashboard before you accept a payment.