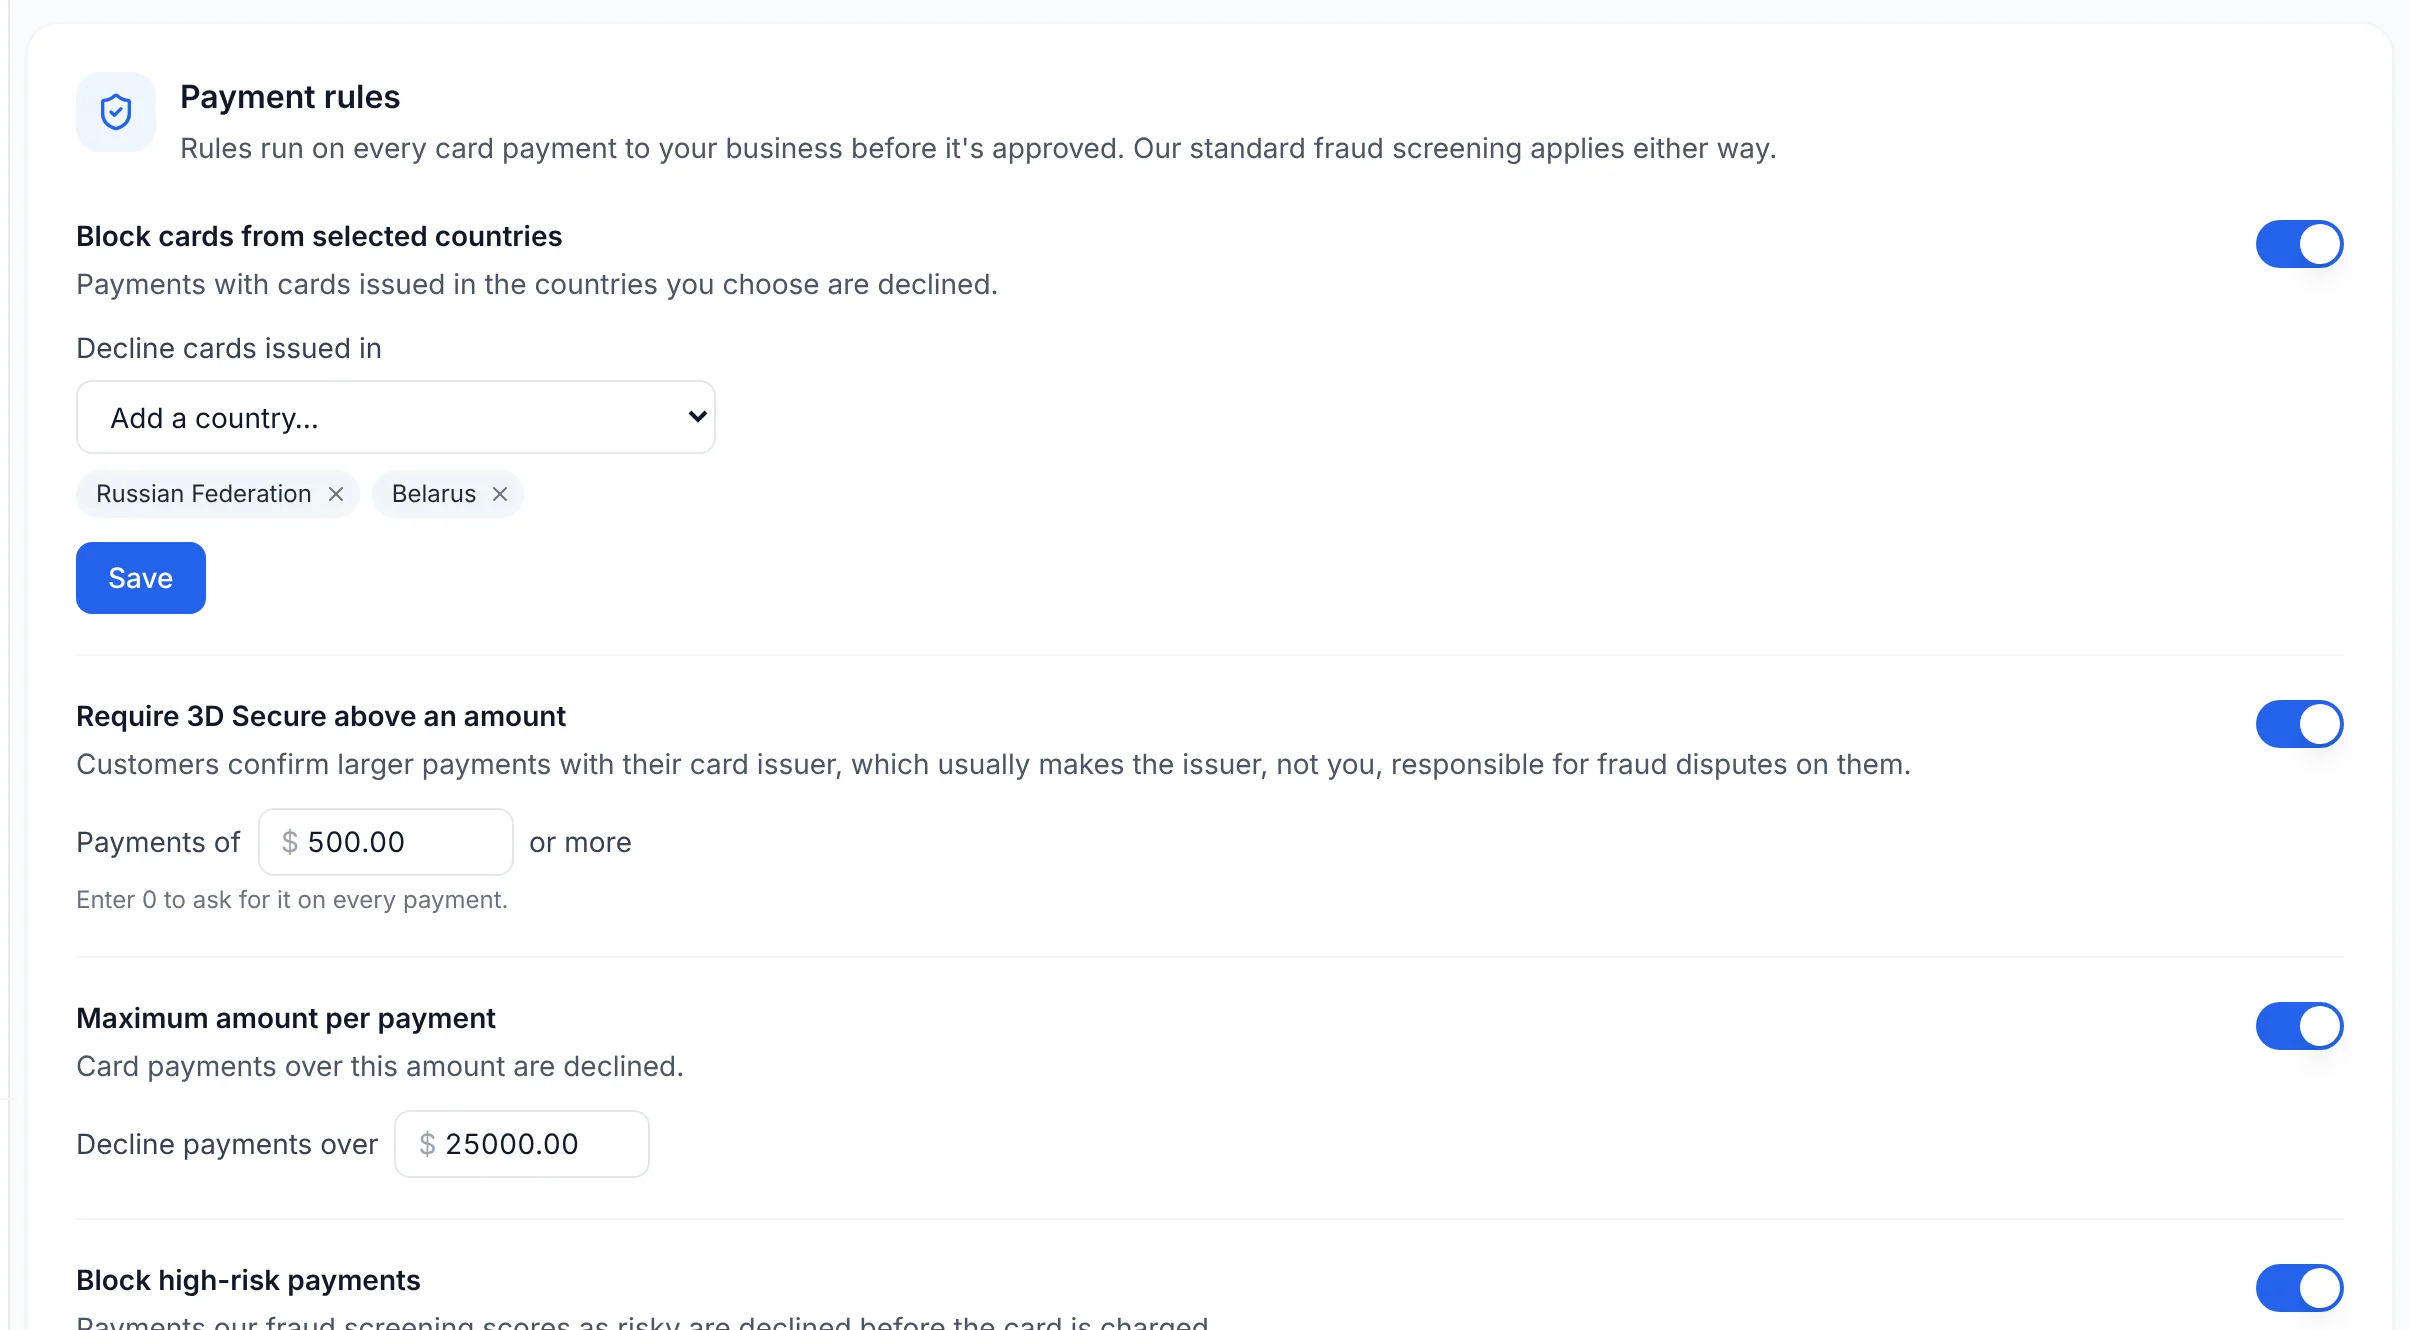
A card policy engine is not what a small business is missing
The pitch for a spend-management platform assumes a company with enough employees that uncontrolled spend is the risk. A small business usually has the opposite problem: two or three people spend money, everyone already knows what everyone bought, and the actual friction is elsewhere — getting paid, paying suppliers, and turning what comes in into usable dollars quickly.
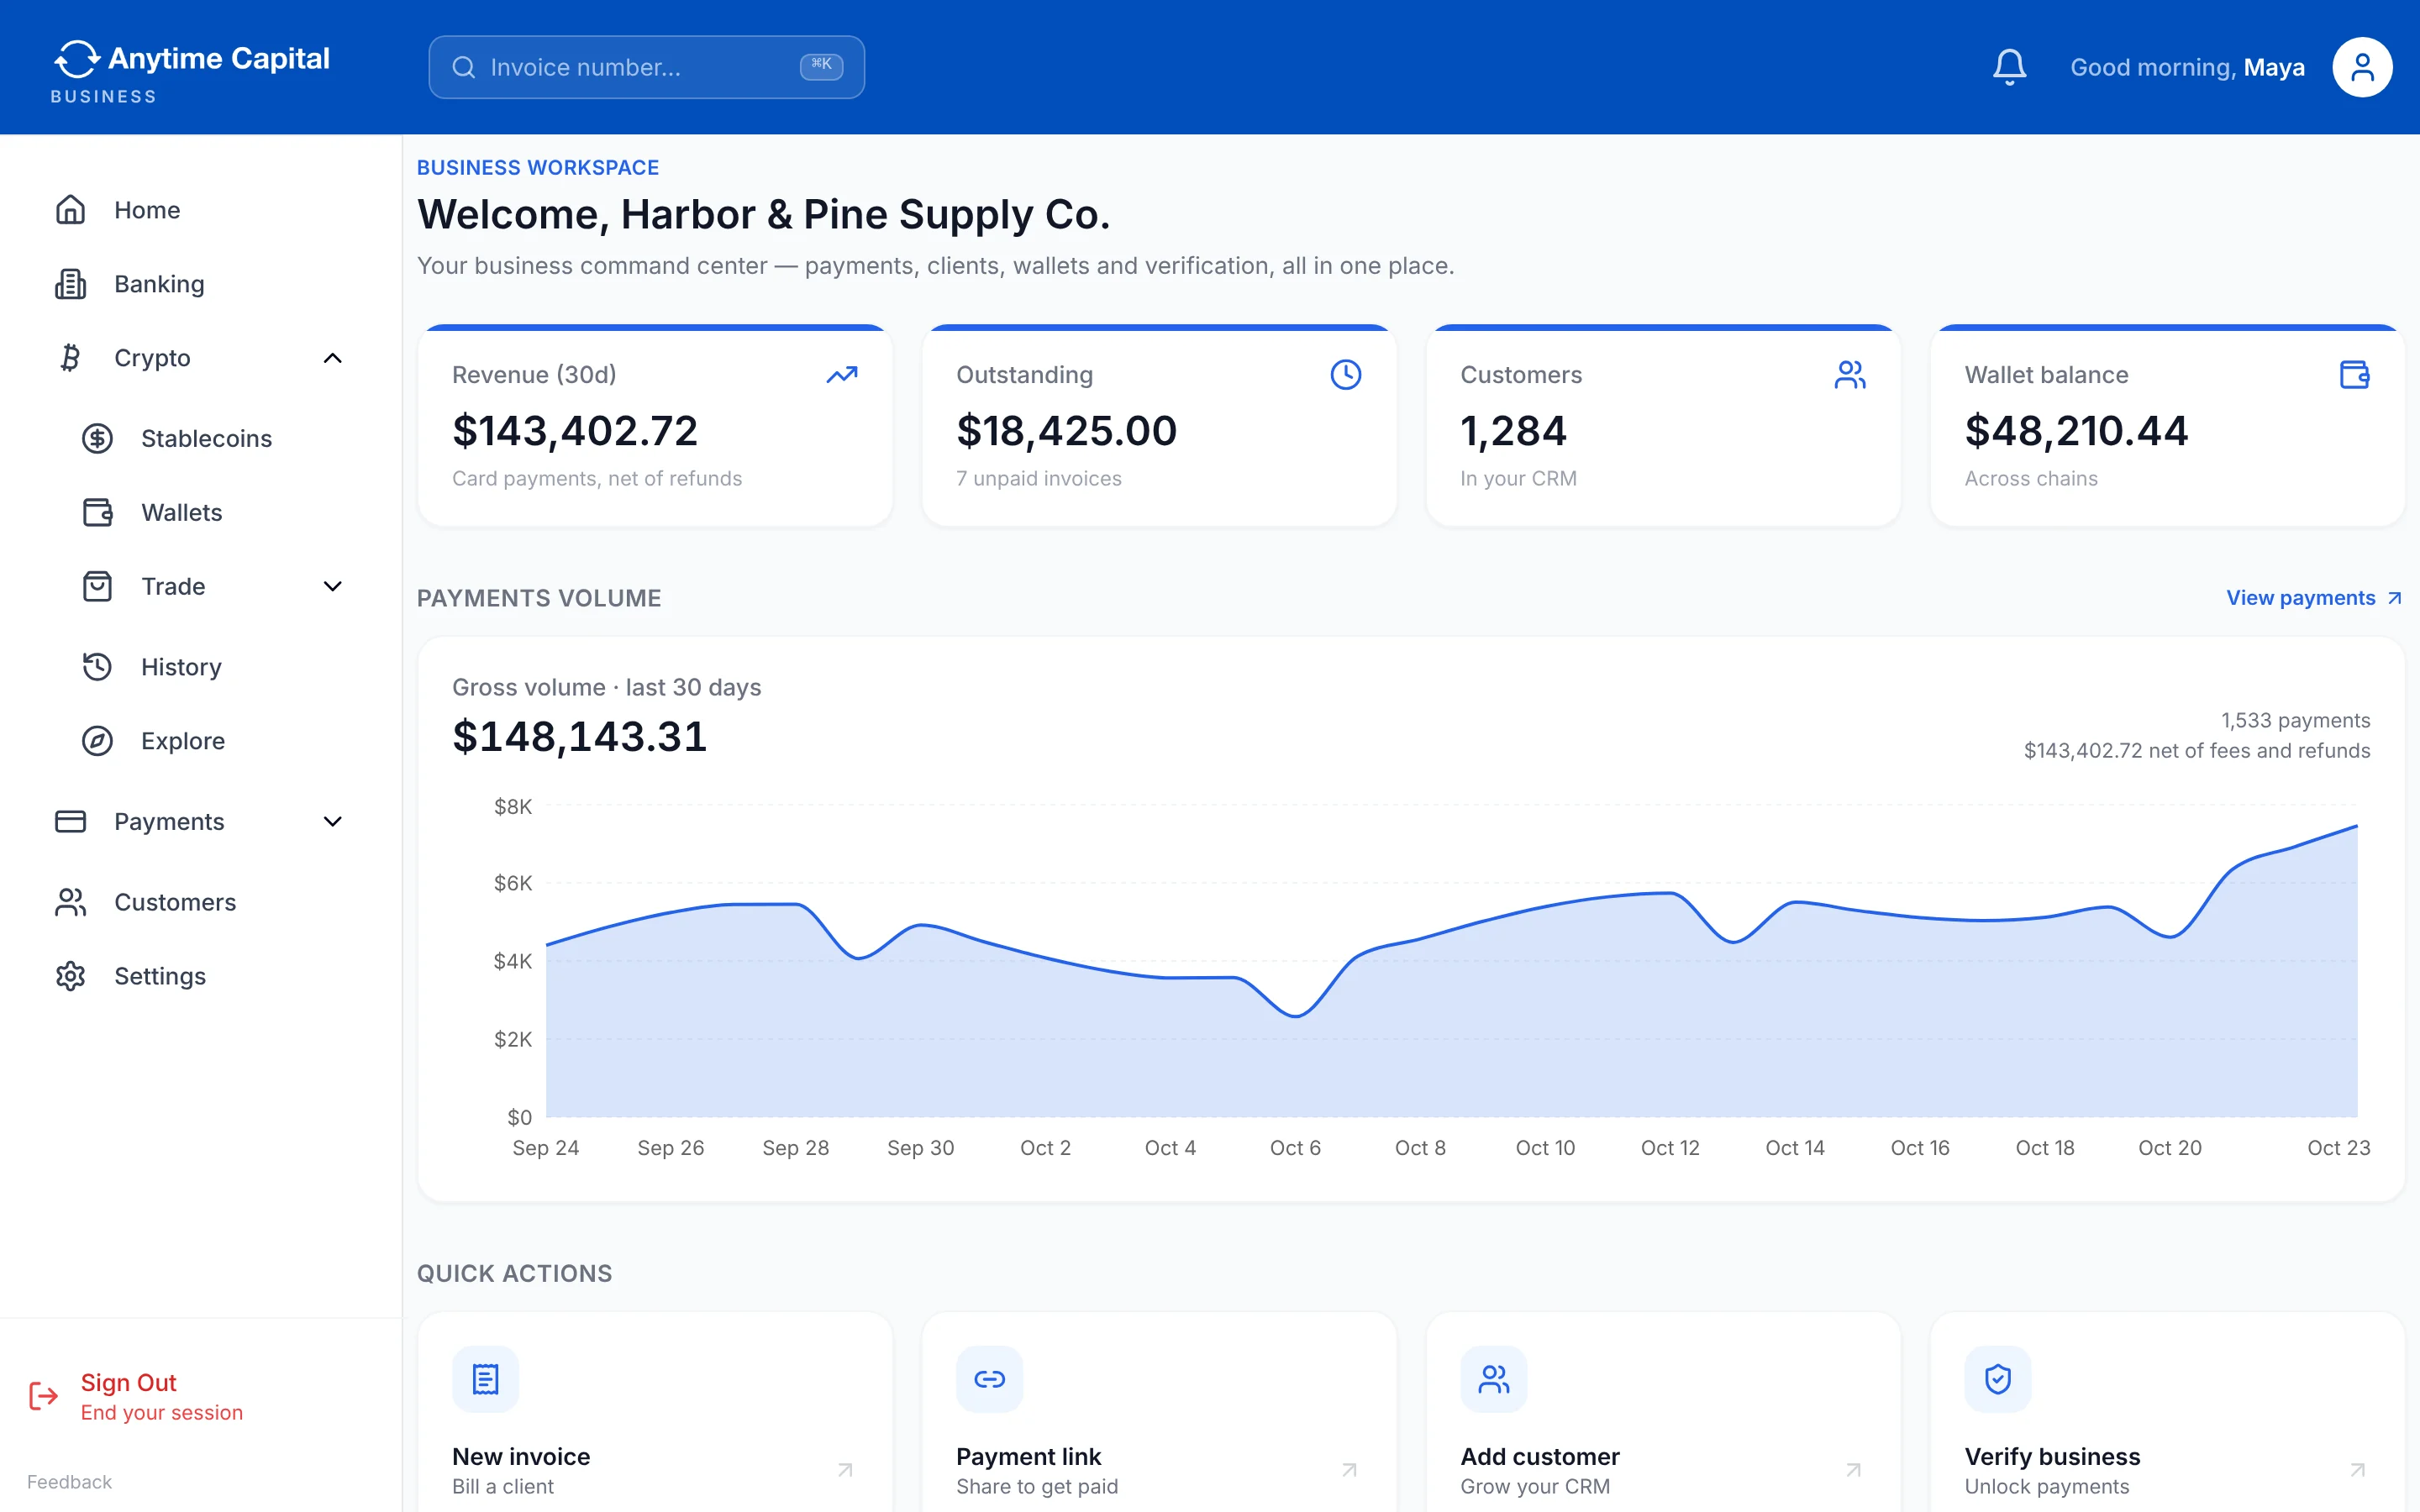
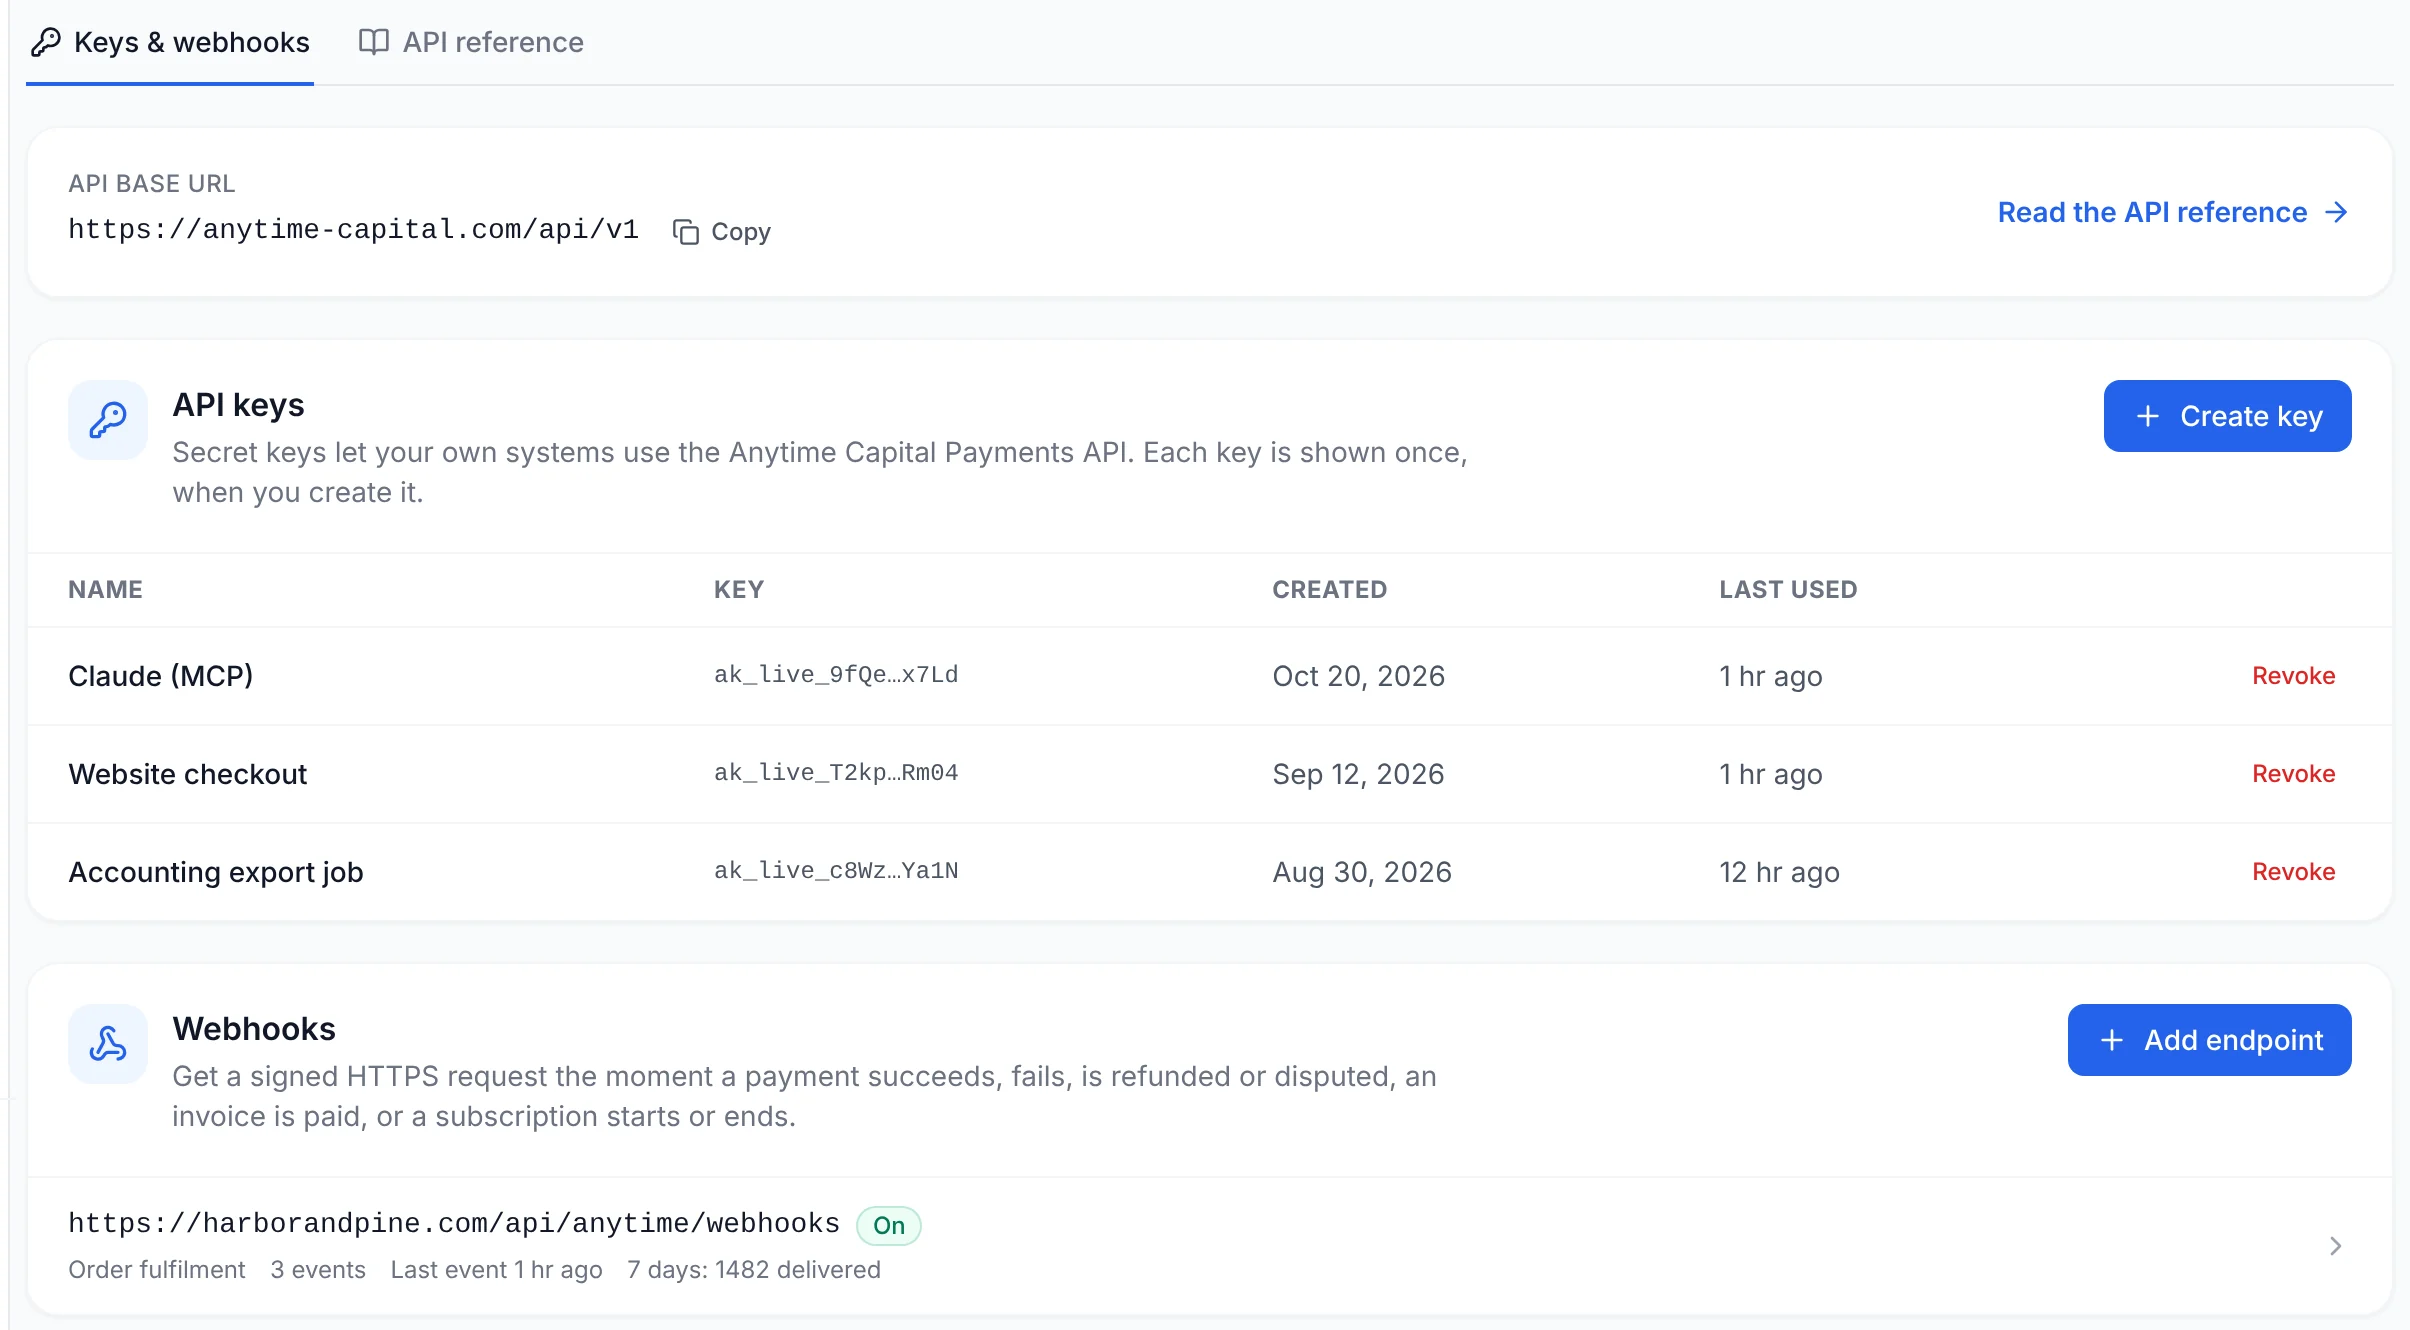
Brex does not process card payments, and its USDC payments, announced in 2025, were not confirmed live as of October 2026. An Anytime Capital business account covers that half directly: card payments at 2.75% + 30¢ paid out to your bank, supplier payouts in USDT and USDC from the business wallet (local rails in 71+ countries), 38+ assets to buy and sell, a free non-custodial wallet, and same-day settlement back to your bank by ACH, Fedwire or RTP.
What a small business actually needs from a crypto account
Small businesses get the worst of the current arrangement. The spend-management platforms are built around venture-backed headcount and card policy, which is not the problem a twelve-person contractor, agency or storefront has. Ramp requires $25,000 in a business bank account before it will open, and the stablecoin products that have arrived hold digital dollars without trading anything else. So the crypto side gets improvised: an owner's personal exchange account, a wallet app on somebody's phone, and a shoebox of screenshots at tax time.
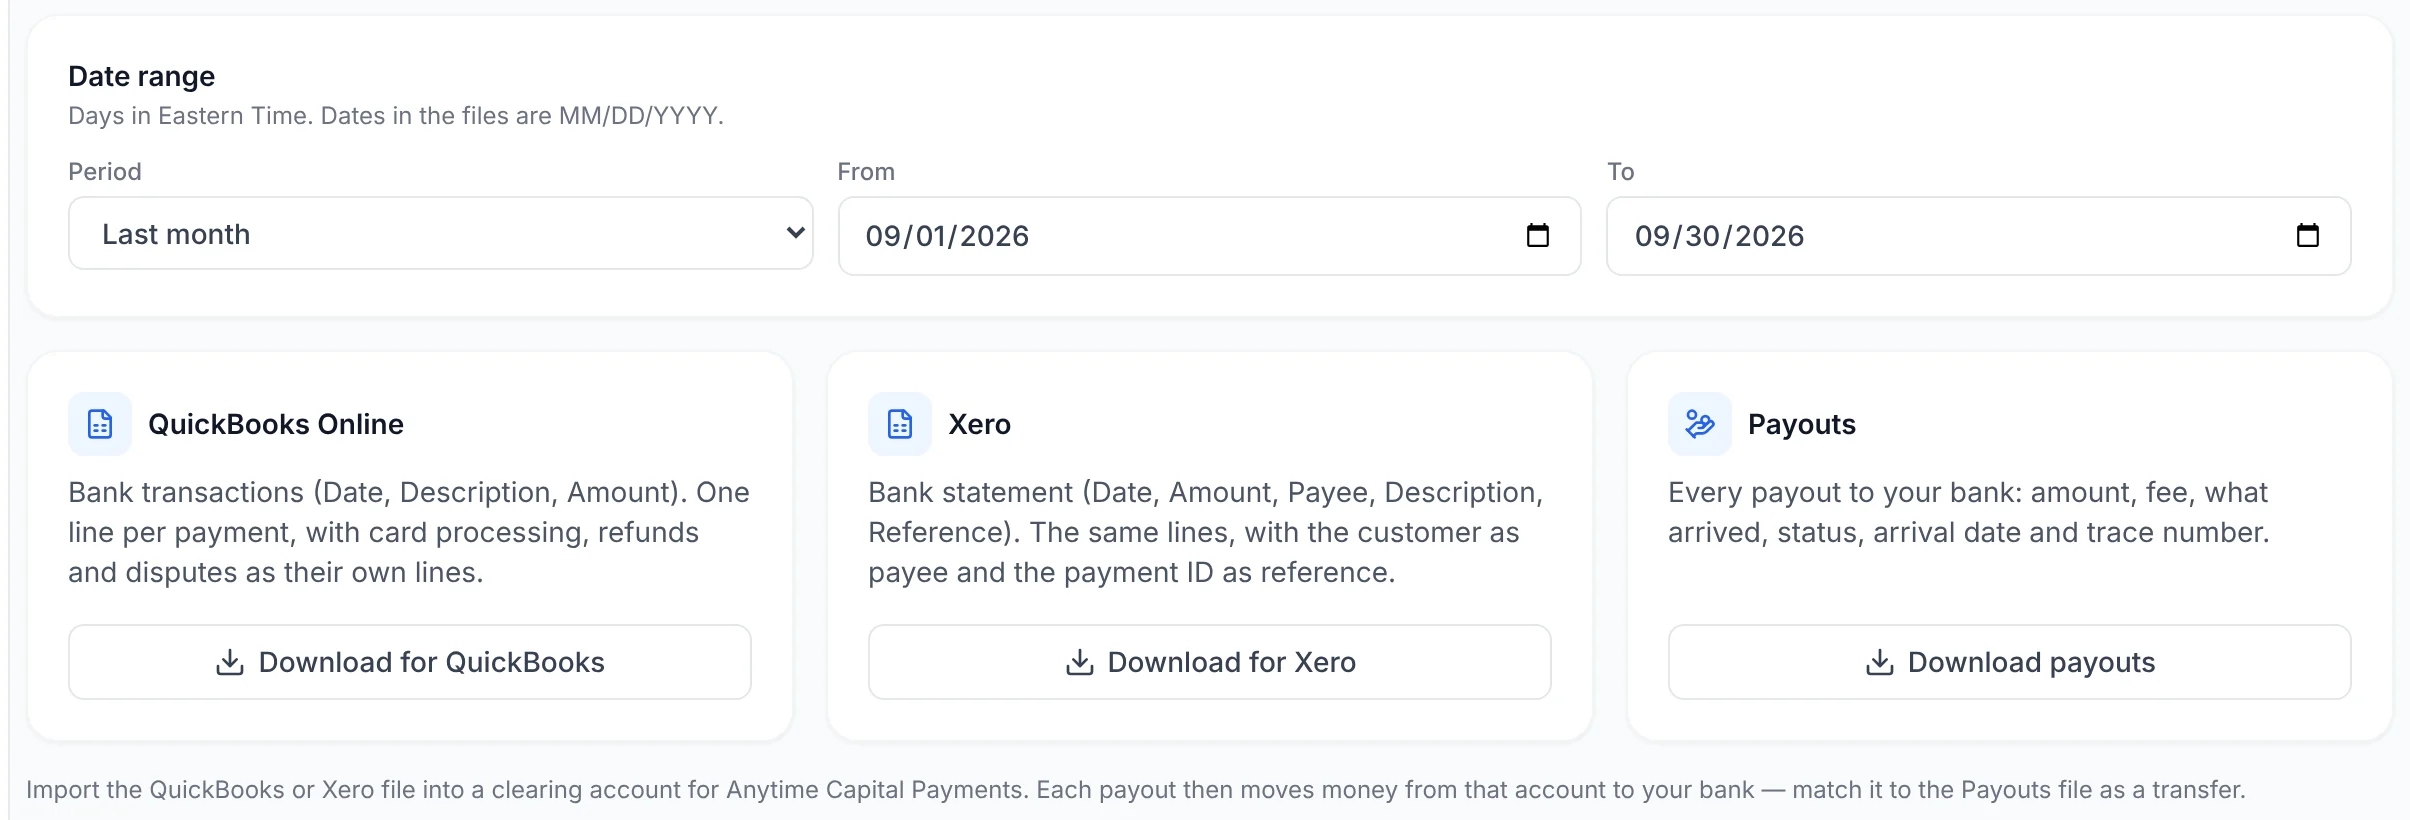
The needs are unglamorous and specific. Buy and sell without a minimum that assumes a Series B. Get dollars back into the business account the same day, not in three. Have somebody answer the phone. Keep the account in the company's name so the bookkeeper and the CPA can actually work from it.
No minimums, no waitlist, and card payments in the same account
Most business accounts are approved the same day the application and KYB documents are complete. There is no waitlist and no requirement to be venture-backed — an LLC with clean formation documents is the ordinary case, not the exception.
The same account takes payments: customers pay by card at 2.75% + 30¢, by ACH on links and invoices, or in USDC and USDT by payment request, and card and ACH payments are paid out to your bank, instant where eligible. Funding the crypto side is deliberately broad too: business wire, business debit and credit cards, ACH, Apple Pay, Google Pay, Cash App, cash by mail, and in-person cash at our Atlanta and Miami branches. When crypto needs to become dollars again, settlement runs same-day by ACH, Fedwire or RTP.
Brex is now a Capital One company. What it does best has not changed.
Capital One announced its acquisition of Brex on January 22, 2026 at a $5.15 billion headline price and completed it on April 7, 2026. For customers, Brex is still what it was: a spend-management platform with corporate cards, expense policy, reimbursements, travel and a business account, built for venture-backed companies and enterprises with entities in several countries.
Its business account is a commercial deposit account at Column N.A., and Brex Vault spreads balances across 24 program banks for up to $6 million in FDIC coverage. Brex charges no fee of its own on domestic or international wires and sends them to 100+ countries, setting the exchange rate on non-USD wires itself; card spend that needs currency conversion carries a markup of up to 3%. For controlling what a large company spends, it is a mature, capable product.
Where Anytime Capital is a different kind of account
Brex is built for money going out. Anytime Capital is built for both directions. We found no card-acquiring product at Brex, so a company that sells online pays a separate processor and waits on its payouts. Anytime Capital Payments takes cards and wallets at 2.75% + 30¢ ($3.05 on a $100 sale) and pays out to your bank, instant where eligible.
Paying abroad works differently too. Brex sends wires. Anytime Capital's payouts to suppliers and contractors on local rails in 71+ countries (SEPA Instant, Faster Payments, PIX, SPEI, UPI, PayNow and mobile money), in minutes to the same day, with SWIFT for the rest; today it sends USDC and USDT from the business's own wallet.
On digital dollars, Brex announced stablecoin payments in September 2025, starting with USDC: accepting stablecoins with automatic conversion to dollars, sending them from USD balances and paying card balances in them. We could not confirm general availability as of October 2026. Anytime Capital takes USDC and USDT at checkout straight to the business's own wallet, where it can hold them, send them or sell them for dollars, and its crypto desk trades 38+ assets at desk-quoted rates.
Running both, or moving over
Larger companies often run both: Brex for cards, policy and travel at headcount, Anytime Capital for getting paid, paying suppliers abroad and handling crypto, with the two reconciling in dollars.
Smaller companies frequently do not need a spend-management suite at all. Anytime Capital covers card payments, stablecoins and crypto today, with a live US business team and custom pricing once card volume passes $1M+ a year.