Answer
How to cash out USDT to a bank account
Quick answer
To cash out USDT, sell it through a regulated platform: send the USDT in, sell it for dollars, and have the dollars paid to a bank account in your own name. On Anytime Capital, a sell order pays out by ACH or RTP, a same-day wire, SWIFT, or a local rail in 71 countries.
Updated October 2026. Evergreen page — refreshed in place as facts change.
- Fastest US payout
- Seconds
- RTP or FedNow, where your bank supports
- ACH / RTP option
- ≤ 2 days
- Instant to 2 business days
- Wire option
- 0–1 day
- Business days, same day if early
- SWIFT option
- 1–3 days
- Business days, outside local-rail countries
- Local payouts
- 71 countries
- SEPA, PIX, SPEI, UPI, mobile money
- USDT on Tron
- ~1 min
- To finalize a TRC-20 deposit
- Payout account
- Your name
- Third-party payouts are refused
- Tax reporting
- 1099-DA
- Broker reporting begins with 2025 sales
Cashing out USDT to a bank account is a sale, not a transfer: banks hold dollars, not tokens, so the USDT has to be sold to someone — a platform, a desk or another person — and the dollars sent to your bank over an ordinary payment rail. Done through a regulated platform with your verification finished in advance, the whole thing takes minutes on the crypto side and anywhere from seconds to a few business days on the bank side, depending on the payout you choose. This page covers the routes, the step-by-step, which network to send on, timing and costs, cashing out outside the US, the checks to expect, the scams that target people cashing out, and taxes.
Payment methods on this page
.svg)
What are your options for cashing out USDT?
Three routes cover nearly every situation:
- A regulated platform — sell USDT for dollars and have them paid to your bank. The standard route for most amounts, and the one this guide walks through.
- A branch or OTC desk — for in-person service or larger blocks, a desk quotes you directly and settles to your account; Anytime Capital has branches in Atlanta, Miami and Houston and an OTC desk for large orders.
- Peer-to-peer sale — selling directly to a buyer. Workable, but you take on counterparty risk and payment-fraud risk that the other two routes remove; treat it as the expert option.
| Route | Typical speed | Best for | Watch out for |
|---|---|---|---|
| Regulated platform | Minutes, plus the payout rail | Most amounts | Verify first; match the network exactly |
| OTC desk | Quoted and settled by arrangement | Large blocks | Arrange before sending; minimums apply |
| Branch desk | One visit for the quote | First or large cash-outs, in-person help | Bring ID; call ahead for large amounts |
| Peer-to-peer | Varies | Experienced users only | Fake payment proof, reversed bank payments |
How do you cash out USDT, step by step?
The platform route, in the order that avoids surprises:
- Open and verify your account first — identity verification is required at any regulated platform, and doing it before you need the money removes the only slow step.
- Open a sell order: choose USDT, the network you will send on, the amount, and how you want to be paid.
- Send your USDT to the deposit address the order gives you, on exactly that network (TRC-20 to a TRC-20 address, ERC-20 to ERC-20); wrong-network transfers can be unrecoverable.
- Wait for the deposit to confirm — about a minute on Tron, seconds on Solana, a few minutes on Ethereum.
- Get paid: the sale completes at very close to $1.00 minus the platform's pricing, and the dollars go out on the rail you chose, to an account in your name.
Cashing out USDT on Anytime Capital
- 1
Sell order
USDT, the network you'll use, the amount.
A minute - 2
Choose the payout
ACH / RTP, wire, SWIFT or a local rail.
Timing shown - 3
Send the USDT
To the order's own address, on that network.
From any wallet - 4
Deposit confirms
The network finalizes it and the sale executes.
Seconds to minutes - 5
Payout sent
To an account in your name, once you're verified.
Seconds to days
Which network should you send USDT on?
USDT exists on several blockchains, and the one you send on changes the cost and the wait — not the value. Tron (TRC-20) is the most common for cashing out: transfers finalize in about a minute, and the fee is paid in TRX. Solana (SPL) is faster still, with fees well under a cent in SOL. Ethereum (ERC-20) takes a few minutes and its fee, paid in ether, can run to several dollars when the network is busy.
The rule that matters more than speed: send on the network the sell order names, from a wallet that holds a little of that network's coin for the fee. A TRC-20 transfer to an ERC-20 address does not arrive, and recovering it, where possible at all, is slow.
How long does cashing out USDT take?
The crypto leg is fast: USDT transfers confirm in seconds to minutes on Tron and Solana, minutes on Ethereum. The sale itself is effectively immediate. The dollars leg is where timing lives — and it depends entirely on the payout rail, plus any compliance review on larger or first-time cash-outs at any regulated platform. See our crypto-to-bank timing guide for the breakdown by asset.
From confirmed USDT to money received, by payout
- RTP / FedNow (US)Seconds
- Local instant railSeconds
- Mobile moneyMinutes
- Domestic wireSame business day
- ACHUp to 2 business days
- SWIFT1–3 business days
Can you cash out USDT outside the US?
Yes — and often faster than a US cash-out, because many countries run instant domestic rails. On Anytime Capital, a sell order can pay out in local currency in 71 countries: euros over SEPA in Europe, pounds over Faster Payments in the UK, reais over PIX in Brazil, pesos over SPEI in Mexico, rupees over UPI in India, Singapore dollars over PayNow, and mobile money such as M-Pesa in Kenya, with SWIFT wires in US dollars or euros to most other countries.
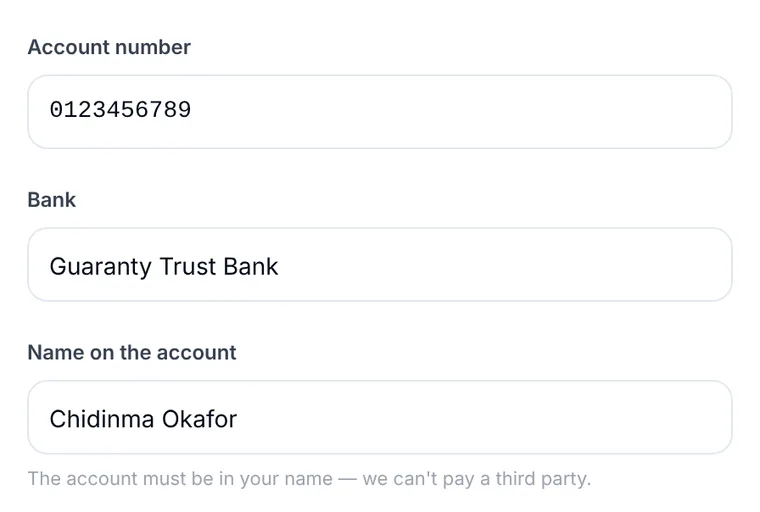
Each corridor asks for the details its rail uses — an IBAN, a sort code and account number, a Pix key, an 18-digit CLABE, a UPI ID, a mobile money number — and the account must be in your own name. Bank details are checked as you type, before the order opens.
What does it cost to cash out USDT?
Count three costs: the network fee to move USDT in (cents to a few dollars depending on chain, 2026); the platform's conversion pricing (varies by provider and method — Anytime Capital quotes your rate before you commit, and /fees-and-limits explains how our pricing works); and the payout cost, which depends on the rail and on what your receiving bank charges for incoming payments — many charge nothing for ACH, and incoming wire fees at US banks are commonly $0–$15 (2026).
One honest warning: 'zero-fee' offers usually live in the conversion spread. Compare the dollars you receive, not the fee line.
What verification should you expect?
Regulated platforms are required under the Bank Secrecy Act to verify identity, monitor transactions, and keep records — the same obligations banks carry. Practically, expect government-ID verification at signup, and possible follow-up questions on large or unusual cash-outs (source of funds is the common one: where the USDT came from, and an exchange statement or invoice that shows it). We run these reviews ourselves: clear, prompt answers release held transactions fastest, and completed verification before you transfer anything keeps the whole process to minutes.
How do you avoid USDT cash-out scams?
People cashing out are a favorite target, because USDT moves irreversibly and dollars sometimes don't. The patterns our compliance team sees most:
- Fake payment proof — a peer-to-peer buyer shows a doctored banking screenshot and asks you to release the USDT before the money has actually arrived.
- Reversible money for irreversible USDT — a buyer pays by a bank transfer or card that is later disputed, leaving you without the dollars or the tokens.
- Dirty money — a buyer pays with stolen funds, and your bank freezes your account while it investigates.
- Fake support — someone posing as a platform agent asks you to send USDT to a 'verification' or 'unlock' address. No legitimate platform asks this.
- Recovery scams — a service promises to retrieve lost or stolen USDT for an upfront fee; the fee is the scam.
- Cash-out favors — a stranger asks you to receive their USDT and send the dollars on. That makes you a money mule, whatever they call it.
How do you cash out a large amount of USDT?
Talk to a desk before you send anything. For six- and seven-figure amounts, an OTC desk agrees a price and the settlement method in advance, so the trade doesn't move the market against you and the compliance questions are answered before the money moves rather than in the middle. Anytime Capital's OTC desk handles exactly this, and our branches in Atlanta, Miami and Houston help in person with verification, a quoted rate and settlement to your account — the route many members prefer for a first large cash-out. Limits at any regulated platform depend on your verification level and compliance review rather than a single published cap.
Do you owe taxes when you cash out USDT?
In the US, selling USDT is a disposal of a digital asset and is reportable, though gain or loss on a dollar-pegged token is typically minimal — what usually matters more is the history of how you acquired the USDT, especially if you received it as payment or swapped other crypto into it. Starting with 2025 sales, US brokers report gross proceeds on Form 1099-DA. Keep records of every step: amounts, dates, transaction hashes. This is general information, not tax advice; a crypto-literate tax professional is worth the fee.
Frequently Asked Questions
Can I send USDT directly to my bank account?
No — banks receive dollars, not tokens. USDT must be sold for dollars at a platform, exchange, or desk first; the dollars then reach your account by ACH, RTP, wire or a local rail, depending on what you choose and what your bank supports.
What's the cheapest way to convert USDT to USD?
Move the USDT on a low-fee network (Tron or Solana rather than Ethereum when the platform supports it), compare conversion pricing on the dollars you actually receive, and choose a payout your bank doesn't charge to receive.
How much USDT can I cash out at once?
Limits at any regulated platform depend on your verification level and compliance review rather than a single published cap. Larger blocks are routinely handled through OTC desks with a direct quote — Anytime Capital's OTC service covers exactly that case.
Can I cash out USDT in person?
Yes — branch and OTC desks handle in-person USDT sales with verification, a quoted rate, and settlement to your account. Anytime Capital's branches in Atlanta, Miami and Houston offer in-person help; it is the route many members prefer for large or first cash-outs.
Why was my USDT cash-out delayed?
The common causes: a wrong-network transfer (the funds never arrived), incomplete verification, a payout account not in your name, or a routine compliance review on a large or first-time transaction. Verify before sending, match networks exactly, and answer review questions promptly.
Can I cash out USDT to someone else's bank account?
No. Regulated platforms pay out only to an account held in the verified seller's own name. If someone asks you to cash out on their behalf, decline — receiving and forwarding other people's money is how money mules are recruited.
What if I sent USDT on the wrong network?
Contact the platform's support immediately with the transaction hash. Whether it can be recovered depends on the networks and addresses involved, and recovery, where possible, is slow. Ignore anyone online who offers to recover it for a fee.
Can I cash out USDT on a weekend?
The sale can happen any day, because blockchains never close. Whether the money lands that weekend depends on the payout: RTP, FedNow and many local instant rails run every day, while wires and ACH wait for the next business day.
Keep reading
Important Disclosures
- Cryptocurrencies and stablecoins are not FDIC-insured deposits, are not bank guaranteed, and can involve risk, including possible loss of value.
- Cryptocurrency transactions are irreversible once confirmed. Verify all details before sending.
- Additional identity verification may be required depending on transaction type and amount.
- Third-party fees, timings, and product details cited on this page are industry-typical figures as of the date shown and may have changed. Verify current details with the relevant institution.
- Anytime Capital is a licensed money services business. Information on this page is educational and is not financial, legal, or tax advice.